

Quick answer:
A VAT compliance audit is a formal Federal Tax Authority review of a registered business's VAT returns against its invoices, accounting records, and supporting documents. Selection is risk-based rather than random. The FTA scores businesses against factors such as filing patterns, declared turnover, industry classification, refund claim frequency, transaction volumes, and past compliance behaviour, with trading, real estate, and cash-intensive sectors seeing higher audit activity.
What Is a VAT Compliance Audit?
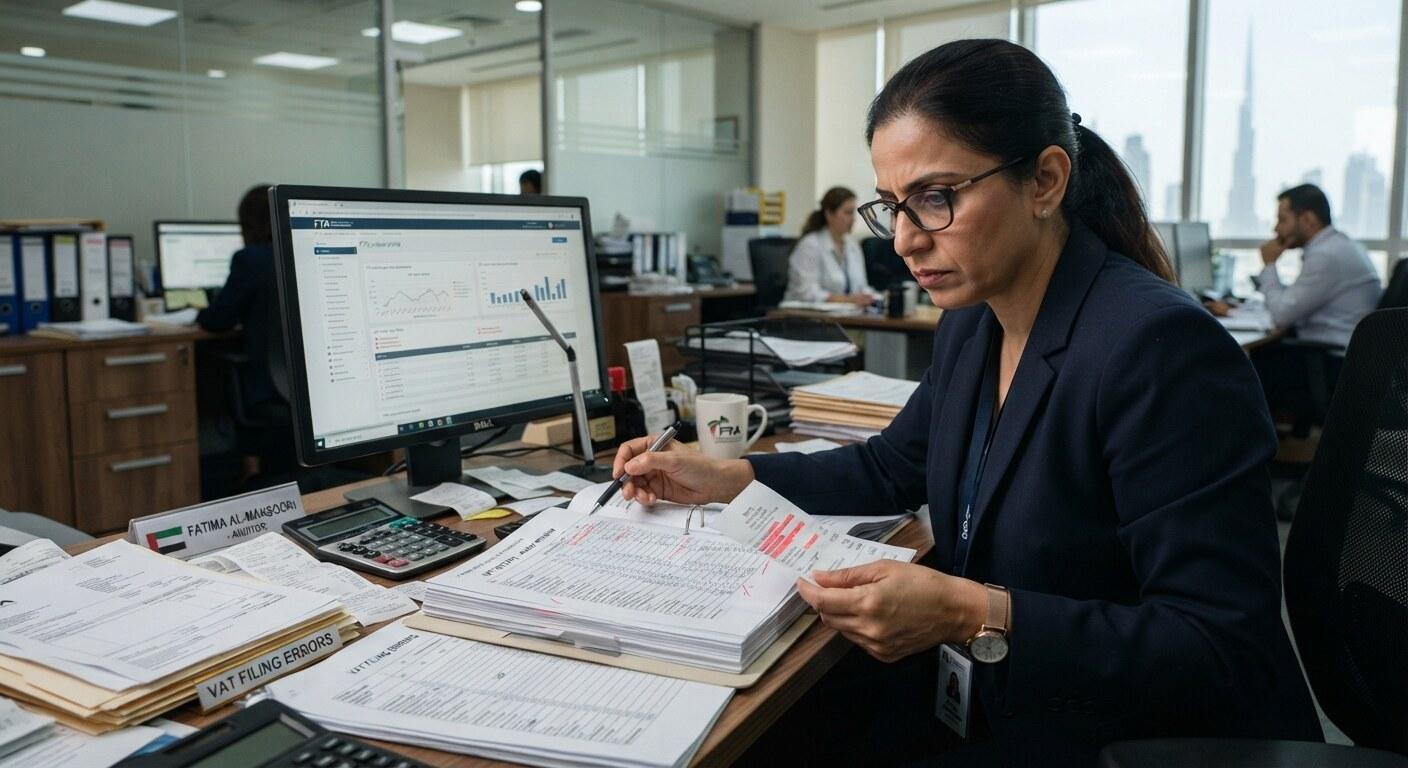
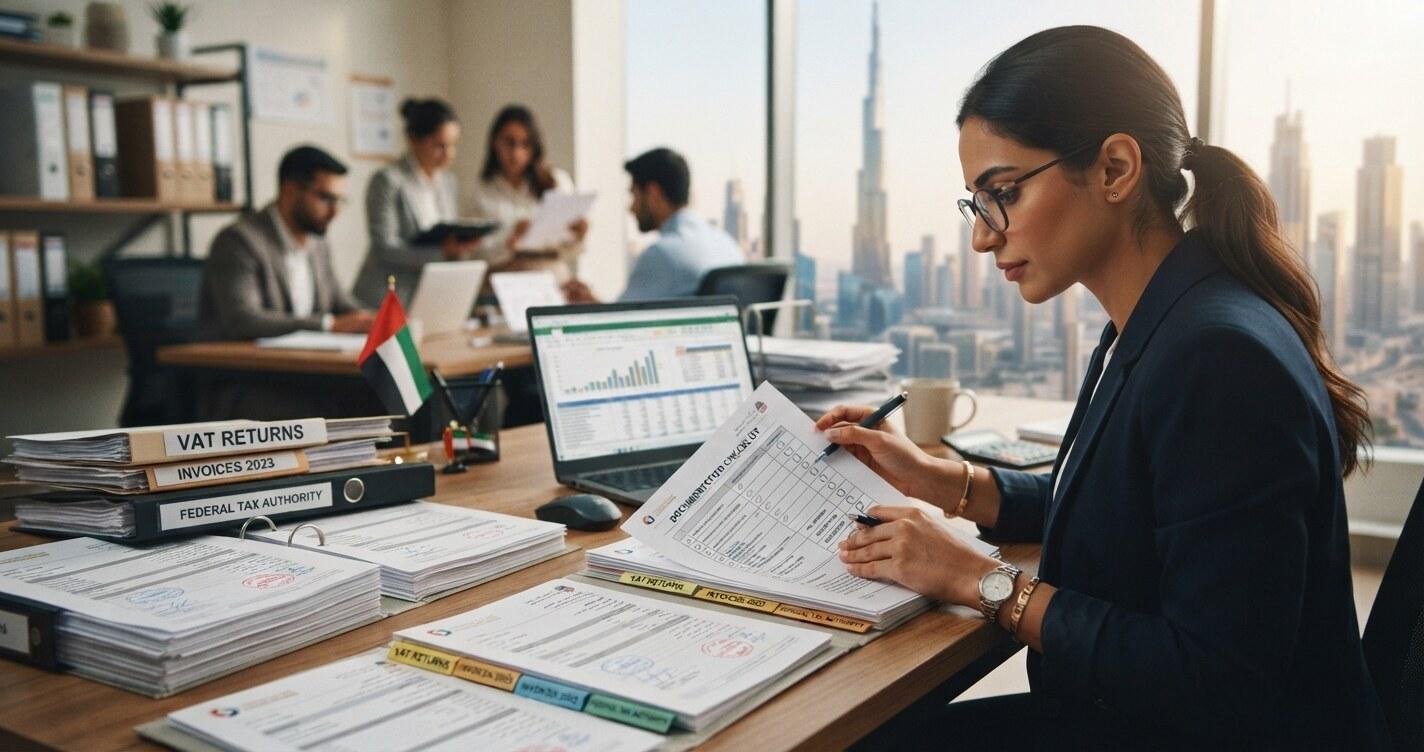
A VAT compliance audit is a formal review carried out by the Federal Tax Authority to check that a registered business has correctly reported and paid the VAT it owes. Auditors compare the figures declared on a business's VAT returns against its underlying records, including tax invoices, credit notes, accounting ledgers, and import or export documentation, to confirm that everything lines up.
Being selected for an audit is not, on its own, an accusation of wrongdoing. It simply means the FTA wants to verify that the numbers on file match reality. Many audits close without any adjustment at all. Others uncover genuine errors, which is exactly why staying audit-ready matters more than trying to predict when a notice might arrive.
Desk Audit or Field Audit: What Is the Difference?
• Desk audit: the FTA requests specific documents and information remotely, and reviews them without visiting the business. Most audits begin this way.
• Field audit: FTA officers visit the business premises, warehouse, or other operating sites in person to inspect records, stock, and processes directly.
A desk audit can escalate into a field audit if the FTA needs to verify something on-site, such as physical stock levels or operational activity that documents alone cannot confirm.
How the FTA Selects Businesses for a VAT Audit
Selection is not random, and it is not based purely on company size. The FTA uses a risk-based model that scores every registered business against a set of indicators drawn from its filing and compliance history. While the exact weighting is not published, the factors known to influence a business's risk profile include:
• Filing pattern signals, such as late submissions, frequent amendments, or returns filed close to every deadline
• Declared turnover and how it compares with a business's licence, sector, and historical figures
• Industry classification, since certain sectors carry structurally higher VAT complexity
• Frequency and size of VAT refund claims, particularly claims that sit well above typical patterns for the sector
• Transaction volumes and the complexity of a business's VAT flows, including cross-border and reverse charge transactions
• Historical compliance behaviour, including any past penalties, disclosures, or discrepancies flagged in earlier returns
The FTA's analytics platform flags anomalies against these indicators and queues businesses accordingly, rather than picking names at will. A single late filing is unlikely to trigger an audit by itself, but a pattern across several of these indicators raises a business's profile considerably.
Which Industries and Business Types Face the Highest Audit Exposure?
Some sectors show up more often in FTA audit activity simply because of how their VAT flows are structured:
• Trading and import-export businesses, due to high transaction volumes and complex VAT treatment across borders
• Real estate businesses, given large transaction values and timing-sensitive VAT recovery positions
• Cash-intensive sectors such as hospitality, retail, and food and beverage, where underreported revenue is a recognised risk area
• Businesses with related-party transactions or group structures, where transfer pricing and intra-group recharges need clear documentation
Falling into one of these categories does not guarantee an audit. It means the underlying risk factors above are watched more closely for businesses operating in that space.
Common Triggers That Push a Business Up the Risk Queue
• Inconsistencies between VAT returns, accounting records, and supporting documents
• Sudden or unexplained movements in declared taxable turnover
• VAT and corporate tax filings that do not align with one another
• Refund claims that exceed what is typical for the business's sector or size
• A pattern of late filings or late payments across multiple tax periods
None of these factors guarantee an audit on their own, but together they build the risk profile the FTA's system scores against. Businesses working with experienced VAT compliance audit in UAE advisors can catch these mismatches through a reconciliation review before the FTA does, which is far less costly than correcting them under audit pressure.
What Happens Once a Business Is Selected
1. Notification. The FTA issues an audit notice specifying the tax periods under review and the documents required. Field audits require at least five business days' notice; desk audits can carry shorter notice periods.
2. Document submission or site visit. For a desk audit, the business submits the requested records through the FTA's channels. For a field audit, FTA officers attend the business premises to review records and, where relevant, physical stock.
3. Review and findings. Auditors cross-check the submitted figures against the business's returns. This can result in confirmation of compliance, requests for further clarification, or a tax assessment where discrepancies are found.
4. Resolution. Where errors are identified, the business may need to settle additional tax, respond to a penalty assessment, or, where the error was self-identified, submit a voluntary disclosure before the FTA raises it.
How Businesses Can Reduce Their Audit Risk
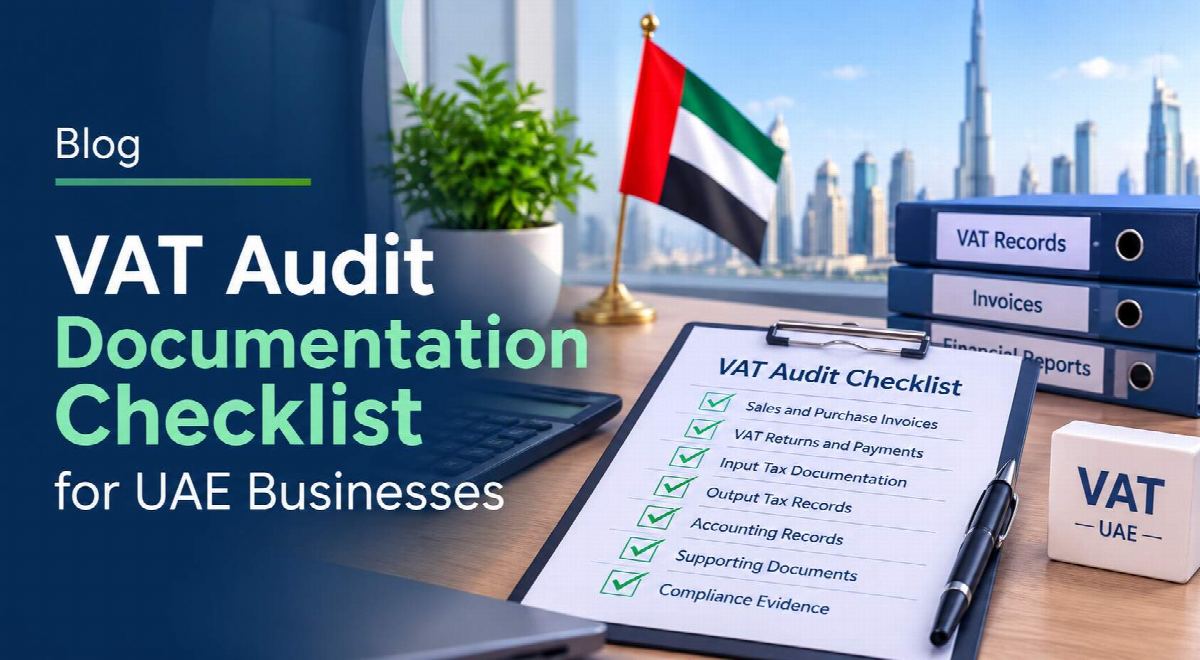
• Reconcile output VAT, input VAT, and the general ledger every month rather than only at filing time
• Keep tax invoices, credit notes, and customs documentation organised and retrievable within your five-year retention window
• Review VAT and corporate tax filings together to catch inconsistencies before the FTA does
• Commission a periodic health check of filed returns, particularly around partial exemption calculations or intra-group transactions
Businesses that are still finalising their licensing structure or reviewing how their operations are set up often find it easier to build these controls in from the start, which is where working with a Business Setup consultant in Dubai can help before compliance issues have a chance to build up.
Frequently Asked Questions
Get Expert Business Support
Share your requirements with us, and our team will help you find the right solution for your business in the UAE.
Address:
Royal House Building - Block A - M8 Floor - Office No 20 - Hor Al Anz - Dubai - United Arab Emirates
Monday To Saturday: 9:00 AM - 8:30 PM
 +971 501 154 886
 Contact on Whatsapp
Social Links:


